
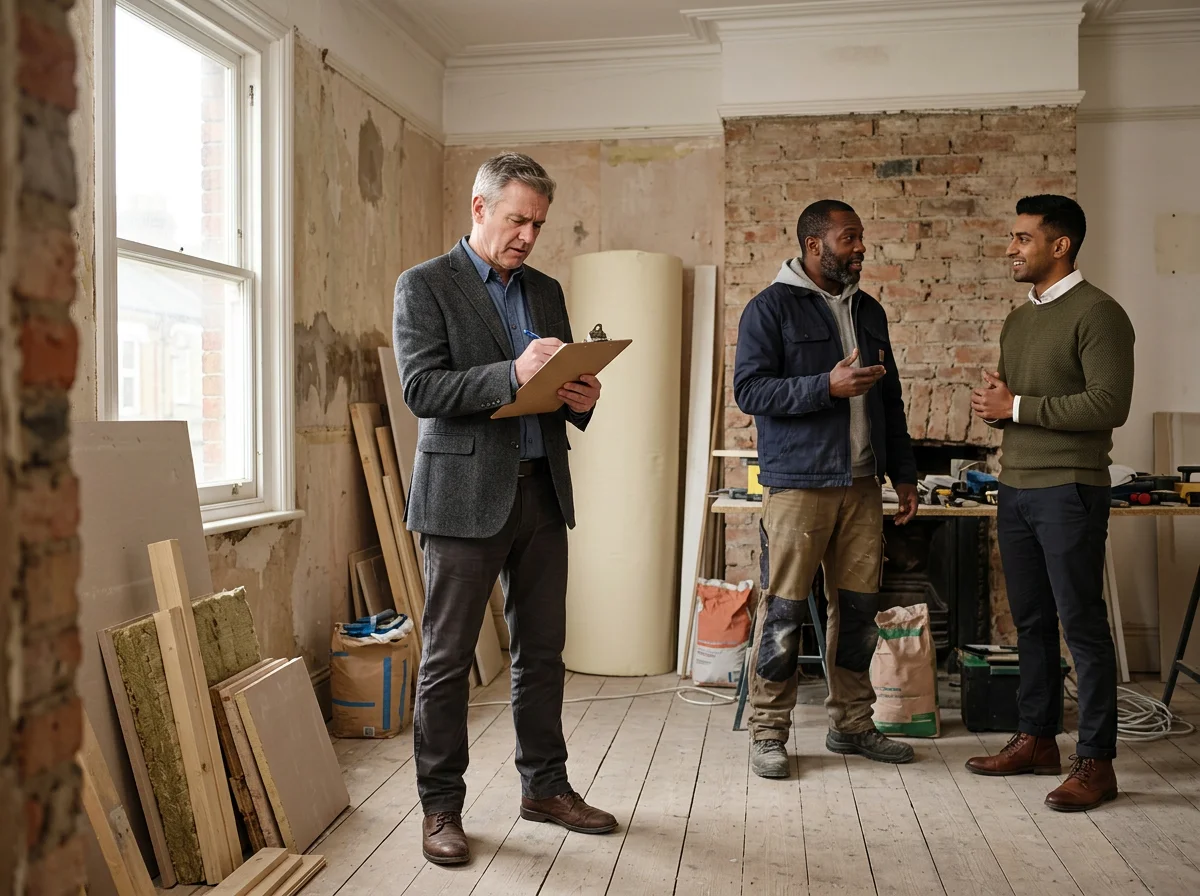
Found a bargain property that needs a little TLC? Perhaps it's got a dated kitchen, no working bathroom, or hasn't been touched since the 1970s.
The problem? Your mortgage lender might not want to touch it either! 😩
Many traditional mortgage lenders are reluctant to finance properties in poor condition, particularly those considered uninhabitable or unmortgageable.
Fortunately, a bridging loan for property renovation could help you purchase the property, carry out the necessary improvements and potentially refinance onto a traditional mortgage afterwards.
Can You Get a Mortgage on a House That Needs Renovating? 🔨
Yes, depending on its condition…
A property needing cosmetic improvements, such as new carpets or a kitchen makeover, may still qualify for a standard mortgage.
However, lenders can become more cautious when properties have:
No functioning kitchen or bathroom.
Significant structural problems.
Serious damp, roof damage or unsafe electrics.
Missing essential services or facilities.
Conditions that make the property unsuitable for immediate occupation.
This is where bridging finance for renovation properties can be particularly useful.
How Does a Bridging Loan Work for a Fixer-Upper? 👷🏼♂️
A bridging loan is a short-term loan secured against property, commonly used to purchase properties that aren't yet suitable for conventional mortgage lending.
Unlike a traditional mortgage, bridging lenders may be willing to consider a property's current condition alongside the proposed renovation works and your plans for repaying the loan.
The process typically looks like this:
Purchase: Use bridging finance to help buy the property.
Renovate: Complete the necessary improvements.
Exit: Repay the bridging loan by refinancing onto a mortgage or selling the property.
Bridging loans commonly run for around 3–12 months, although terms vary between lenders.
Interest can sometimes be rolled up rather than paid monthly, helping preserve cash during renovations. However, the interest still accrues and must be repaid.
There’s not usually any monthly payments, instead interest is added each month to the balance. You only pay interest for as long as you keep the loan for, so the sooner you pay the bridge back, generally the cheaper it will be.
Example: 75% LTV bridging loan for a fixer-upper 📈
Purchase price: £150,000
Net loan amount: £98,000
Monthly interest rate: 0.75%
Interest amount over 12 months: £10,125
Average monthly interest cost: £843
Lender completion fee: £2250 (added to the loan on completion)
Broker completion fee: £1995 (added to the loan on completion)
So, in this example, the client buys the property for £150,000
He puts down a £52,000 deposit, and spends £30,000 on renovations
He anticipates he’ll complete this within 3 months, so factors in 3 months of interest (approximately £2,531)
After the works, he has the property re-valued at a new value of £240,000
This generates a gross profit of £53,224 after 3 months 💸
Don’t forget to factor in:
Stamp duty costs (including surcharge for ltd company purchases or additional-owned properties)
Valuation fees
Estate agent fees
Auction fees (if applicable)
Can You Get Bridging Finance for an Auction Property? 🙋🏼
Absolutely — subject to lender approval!
Property auctions can be a great place to find renovation projects, but they often come with tight completion deadlines.
Many auction purchases require completion within approximately 28 days, although the legal pack determines the actual deadline.
✅A bridging loan for an auction property may provide a quicker route to funding than a traditional mortgage, particularly if the property needs significant refurbishment.
⚠️However, bridging finance isn't guaranteed, so it's important to arrange your funding strategy and review the auction legal pack before bidding.
What Happens After the Renovation? 💸
Before taking out a bridging loan, you'll need a clear exit strategy — essentially, how you intend to repay it.
The two most common options are:
Refinancing: Once the property is suitable for mortgage lending, you may be able to replace the bridging loan with a residential or buy-to-let mortgage with the increased value.
Selling: If you're renovating to sell, the sale proceeds can be used to repay the bridging loan.
Remember that refinancing is subject to lender criteria, including affordability, property valuation and potentially minimum ownership requirements. If your exit is delayed, additional interest or fees may apply. A good mortgage broker will have your exit strategy checked beforehand, e.g if refinancing, they will do a decision in principle beforehand to check your eligibility.
How Celtic Finance Can Help 🤗
At Celtic Finance, we specialise in bridging finance, refurbishment loans and specialist property mortgages.
Whether you're purchasing an unmortgageable house, renovating an investment property or buying a fixer-upper at auction, we can help explore suitable finance options.
We work with specialist lenders who may consider properties that traditional mortgage lenders won't.
Found a property with potential but struggling to finance it?
Contact Celtic Finance today to discuss your project and explore your bridging finance options.
Frequently Asked Questions: 🎤
Can I get a bridging loan on an uninhabitable house?
Potentially, yes. Some specialist bridging lenders consider properties without functioning kitchens, bathrooms or other essential facilities, depending on their condition and the proposed works.
Can I get a bridging loan to buy and renovate a property?
Yes. Bridging finance can help fund a property purchase, while some refurbishment finance products may also contribute towards renovation costs.
How much deposit do I need for a bridging loan?
Deposit requirements vary. Some lenders may offer around 70–75% loan-to-value against the property's current value, although the available loan depends on the property, borrower and lender. Fees and retained interest can reduce the net amount available.
Can I refinance after renovating a property?
Potentially. Once the property meets mortgage lending requirements, you may be able to refinance, subject to valuation, affordability and the new lender's criteria.
Can I get a bridging loan with bad credit?
Yes, this is still possible with certain lenders. Sale is usually preferred as an exit strategy if you have a lot of adverse credit, as it doesn’t rely on a mortgage which may be difficult to obtain until your credit improves. However, most bridging lenders won’t shy away if there’s adverse credit, they will just want to be comfortable that you can repay the loan within 12 months.
Do I need previous experience?
With some lenders, yes. However, many will accept applicants with no prior experience. They will just want comfort that you have contractors, or a team behind you to help. If you’re a tradesperson, this is often looked at positively too. Past experience is only usually asked for when it’s a large-scale project, otherwise you may need a project manager to assist.
Bridging finance is short-term borrowing secured against property. Interest, fees and other charges apply. Failure to repay the loan may result in repossession. All finance is subject to lender criteria, valuation and approval.
Your property may be repossessed if you do not keep up repayments on a mortgage or other loan secured on it.
If you do not repay your bridging loan before the end of the term, you risk reposession from the lender - this is why the exit strategy is extremely important, and having an experienced broker on your side can make all the difference.
Drop us a message if you have any questions or potential property projects coming up! 📲
